VA Home Loans & Veteran Homebuying in Lake Norman, NC.
You served our country. North Carolina served more than 600,000 veterans with a welcoming home, and you can be one of them. This guide covers VA home loan basics, NC veteran benefits, base connections, and PCS moves from a REALTOR who wore the uniform herself.
Your VA benefit is powerful. Let's put it to work.
The VA home loan program helped service members buy homes for over 80 years, and it is one of the strongest homebuying tools available. If you are an active-duty service member, a veteran, a qualifying National Guard or Reserve member, or an eligible surviving spouse, the benefit is yours by right of service. The goal of this page is simple: explain how it works, what North Carolina adds on top, and how to use it without stress.
Tiffany Huntoon, a REALTOR with eXp Realty and The Lauren Rocco Team, served in the U.S. Army and U.S. Air Force (military intelligence analysis) and is married to a retired Army veteran. She has moved her own family across the country on military orders and now helps veterans and military families find homes around Lake Norman and the Charlotte metro. This guide is general information, not financial advice. Your VA-approved lender owns the numbers, and your county veterans service officer owns the benefit details, and Tiffany will connect you with both.
What a VA Loan Is and How It Works
A VA-backed home loan is a mortgage issued by a private lender and guaranteed by the U.S. Department of Veterans Affairs. That guarantee is what allows lenders to offer terms civilians often cannot get: no down payment for full-entitlement borrowers, no monthly PMI, and generally competitive rates.
Who is eligible?
- Veterans and active-duty service members who meet minimum service requirements (for example, 90 days of active duty during wartime or 181 days during peacetime) and were discharged under conditions other than dishonorable.
- National Guard and Reserve members with six creditable years in the Selected Reserve, or qualifying active-duty time.
- Surviving spouses of veterans who died in service or from a service-connected disability, and spouses of service members who are MIA or POW, in most cases while not remarried.
What the lenders look at
The VA does not set a minimum credit score, though most VA-approved lenders want to see around 620. You also need sufficient, stable income, a debt-to-income ratio the lender can approve, and the home must be your primary residence. A VA appraisal protects your side of the deal: it confirms the property's value and flags safety issues before you commit, which is exactly the kind of protection you want in a market moving as fast as Lake Norman.
The practical move is to work with a VA-approved local lender. Tiffany keeps a short list of lenders who know VA rules and the NC contract process, and she will happily make warm introductions before you look at a single home.
No Down Payment
Eligible buyers with full VA entitlement can purchase with zero down, and there is no private mortgage insurance (PMI) to pay each month.
More Favorable Terms
VA-backed loans generally offer competitive interest rates, no monthly mortgage insurance, and protections like the appraisal process that keeps the home and the contract honest.
The Funding Fee, Explained
The VA charges a one-time funding fee on most loans (2026 purchase rates start at 2.15% for first use with less than 5% down). It can be rolled into the loan, and it is waived for veterans receiving VA disability compensation.
Eligibility, Confirmed Early
Your Certificate of Eligibility (COE) confirms which benefit you qualify for. Tiffany can connect you with a VA-approved local lender who pulls your COE and walks through your numbers before you tour a single home.
NC Veteran Benefits Worth Knowing
North Carolina is home to roughly 620,000 veterans, and the state backs that welcome with real benefits. The big one for homeowners is the disabled veteran property tax homestead exclusion (N.C. G.S. 105-277.1C): qualifying veterans are exempt from property taxes on the first $45,000 of the appraised value of their primary residence.
Who qualifies
- The veteran must be a North Carolina resident and own and occupy the home as a permanent primary residence as of January 1 of the tax year.
- The veteran must hold a 100% permanent and total service-connected disability rating certified by the VA, or receive benefits for specially adapted housing. A partial rating does not qualify for this specific exclusion.
- A never-remarried surviving spouse of a qualifying veteran can continue receiving the exclusion in many cases.
How to apply
You apply through your county tax office, not the state: complete the NCDVA-9 certification form through your county veterans service office, then file it with the AV-9 application by the county's deadline (typically June 1) to apply for that tax year. Tiffany recommends putting this on your calendar the moment your offer is accepted, because it is easy to file and easy to forget.
Your county veterans service officer (VSO) is the best first phone call for this and for any NC veterans benefit question. Tiffany can point you to the VSO office in Mecklenburg or Iredell County depending on where you buy, and she helps veterans line up the paperwork during the transaction so nothing slips through closing.
North Carolina's Military Presence and the Lake Norman Draw
Fort Bragg (Fayetteville)
About 140 to 160 miles from Lake Norman, a drive of roughly 2 hours 45 minutes to 3 hours. The Army's largest installation by population and the fort known as Fort Liberty from 2023 to 2025.
Camp Lejeune (Jacksonville)
Marine Corps Base Camp Lejeune sits about 265 to 280 miles east, roughly 4 hours 30 minutes from the Lake Norman area. Pair it with nearby MCAS New River and Cherry Point on the coast.
Seymour Johnson AFB (Goldsboro)
About 235 to 245 miles from the northern lake, roughly 3 hours 40 minutes to 3 hours 50 minutes. Central and eastern NC duty stations like these make Charlotte the natural big-city hub.
Why Lake Norman is so popular with military families
The honest answer involves a commute tradeoff. A daily drive from Lake Norman to Fort Bragg is impractical, so Lake Norman leans toward service members stationed locally, families where one spouse works in Charlotte's defense-adjacent economy, veterans settling into civilian careers, and retirees choosing quality of life. Uptown Charlotte is roughly 20 to 25 minutes south, home to banking, tech, healthcare, and a growing defense and aerospace sector.
What Lake Norman gives a military family is the life you served to protect: waterfront recreation, top-rated schools in districts like Mooresville Graded, Hough and North Meck, walkable small towns like Davidson and Cornelius, strong youth sports for kids who need structure and community, and neighborhoods where neighbors actually know each other. Veterans often tell Tiffany it feels like the first place that felt like home.
Moving on orders? Build the plan backward from your report date.
A PCS (permanent change of station) is a full-scale operation, and the families who handle it best treat it like one. Orders usually arrive 8 to 12 weeks before your report date, which gives you a tight, real window: roughly 90 days to set up household goods, school transfers, BAH adjustments, and a home plan.
A realistic PCS home timeline
- 90 days out: Get your COE and a VA pre-approval. Start the home search with Tiffany while household goods are still being scheduled.
- 60 days out: Military OneSource's household goods (HHG) shipment or a Personally Procured Move (PPM) is booked; lock your decision on buying vs. renting.
- 45 days out: Offers are written on the buy side, or temporary housing is confirmed on the rent side. School enrollment paperwork starts.
- 30 days out: Inspections, appraisal, and underwriting run while you pack. Closing before report date is the goal.
Buying before you arrive is very doable with a VA loan: the VA requires you to occupy the home as your primary residence, generally within 60 days of closing, and PCS families routinely close remotely using virtual tours, a power of attorney, and electronic closing. House-hunting leave (permissive TDY) and Temporary Lodging Expense (TLE) reimbursement are tools worth asking your chain of command about.
For the full moving plan, school calendars, and logistics, visit Tiffany's relocation resources and the detailed out-of-state relocation guide, which covers virtual buying, timeline planning, and what to do before the moving truck arrives.

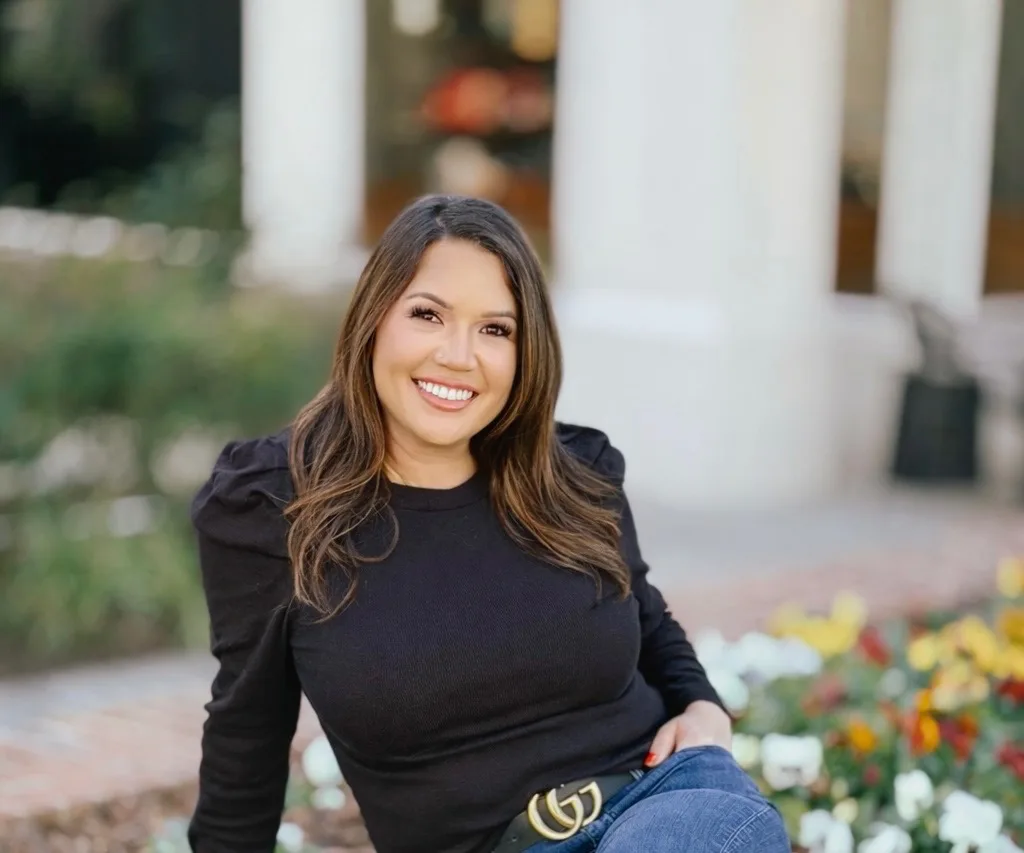
She has lived your transition. Literally.
Tiffany Huntoon is not a veteran-friendly agent who read a brochure. She is a veteran: an enlisted soldier in the U.S. Army and an Airman and officer in the U.S. Air Force, with a military intelligence analysis background. Her husband is a retired Army veteran, which makes their household a retirement tale only the military can write: two careers on orders, two big cross-country relocations, two high-school athletes re-rooted midseason, and two dogs who made every move with them.
That lived experience shows up in the work. She understands why an assignment length changes your buy-versus-rent math, why BAH feels different on paper than in a budget, why a spouse starting a new job needs a home near 485, and why kids settling into a new school district need a yard and a routine fast. It is the reason her veteran clients describe her, in their own words, as calm, caring, kind, and thorough.
As a REALTOR and Production Partner with The Lauren Rocco Team under eXp Realty (NC License #363052), Tiffany pairs that personal understanding with a full local team: marketing muscle, transaction support, school data, and lender referrals. She serves Huntersville, Cornelius, Davidson, Mooresville, and greater Charlotte.
"Calm, caring, kind, thorough." That is how a veteran client described Tiffany Huntoon after buying their Lake Norman home, and it is the exact temperament a PCS family needs at the end of a long move.
Real client feedback shared with permission, praising Tiffany's demeanor and her military veteran background.

Frequently Asked Questions
Can I use a VA loan in North Carolina?
Yes. VA-backed home loans are available in every state, including North Carolina. Tiffany Huntoon, a REALTOR with eXp Realty and a veteran herself, works with VA-approved local lenders every week who help active-duty, veteran, Reserve, and National Guard buyers use their VA benefit all around Lake Norman and the Charlotte metro.
What are North Carolina property tax breaks for veterans?
North Carolina offers a disabled veteran property tax homestead exclusion under G.S. 105-277.1C: qualifying veterans with a 100% permanent and total service-connected disability rating (or who receive specially adapted housing benefits) are exempt from property taxes on the first $45,000 of their primary residence appraised value. It is applied through your county tax office using NCDVA-9 and AV-9 forms, usually due by June 1.
Is Lake Norman close to Fort Bragg?
Lake Norman sits about 140 to 160 miles from Fort Bragg near Fayetteville, a drive of roughly two hours and 45 minutes to three hours depending on which lakeside town you choose. The installation was known as Fort Liberty from 2023 to 2025 and is again Fort Bragg. Many military families who work at Fort Bragg or in the surrounding area choose to live toward the Charlotte side and commute on a less frequent schedule.
Can a veteran buy with $0 down in Lake Norman?
Yes, if you have full VA entitlement, you can buy with no down payment. There is no loan limit for full-entitlement borrowers, and the VA guarantee means no PMI. Your credit, income, and debt ratios still matter, which is why Tiffany helps veterans get pre-approved with a VA-approved lender before the home search begins.
Do I need a special lender for a VA loan?
You need a VA-approved lender, meaning a lender that is authorized to originate VA-backed loans. Not every mortgage company is. Tiffany keeps a short list of local VA-approved lenders who know the Lake Norman market, funding fee rules, and NC-specific closing process and can move on a PCS timeline.
What credit score do I need for a VA loan?
The VA does not publish a minimum credit score, but most VA-approved lenders want to see a score around 620. Credit history, sufficient income, and a debt-to-income ratio lenders can approve matter more than the exact number. A VA-approved local lender can review your profile and tell you where you stand.
Can a surviving spouse use a VA home loan?
In many cases, yes. Surviving spouses of veterans who died in service or from a service-connected disability, and spouses of service members who are MIA or POW, may be eligible for a VA loan if they have not remarried, with some exceptions for remarriage after age 57. Your county veterans service officer or a VA-approved lender can confirm your specific eligibility.
Should I buy or rent during a PCS to the Lake Norman area?
It depends on your assignment length. A common rule of thumb is to rent when you expect to be in an area under three years and consider buying when you will stay three to five years or more. VA loans, no-down-payment buying, and temporary rental options all fit into a PCS plan, and Tiffany helps families weigh the math for their own orders.
More Resources for Your Move
The VA Loan Guide, In Depth
Funding fees, entitlement, loan limits, and the myths that scare buyers and sellers away from VA offers.
Relocation Resources
School lotteries, remote tours, temp housing, and the full Lake Norman moving playbook.
Moving From Out of State
The honest 90/60/30 timeline and how to buy sight-unseen with confidence.
First-Time Buyer Hub
Down payments, the NC due diligence fee, and the steps between pre-approval and keys.
New to the market? See the latest numbers in the Lake Norman Market Report.
Semper Fi to your home search.
Call Tiffany Huntoon at (706) 421-8928, email Tiffany@laurenrocco.com, or book a zero-pressure consultation.
Start Your VA Home Search